Freshly Picked, October 19, 2026

Freshly Picked Insights
- Restaurant Cost Savings: How Multi-Unit Brands Can Reduce Operating Costs
- How Restaurant Indirect Costs Quietly Erode Profitability
- How to Optimize Your Restaurant Workflow
Poultry
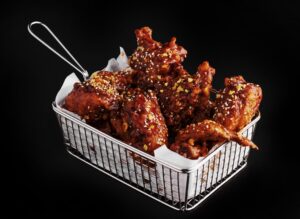
Poultry pricing continues to diverge by cut: breasts, tenders and wings softened, while thighs and leg quarters strengthened. Production is slowing as producer margins compress, despite strong consumption. Multiunit buyers should review cut specifications and menu exposure across concepts before applying a single poultry-cost assumption.
Outlook: Strong consumption and a slower production pace create future firming risk, even while selected white-meat cuts offer near-term relief.
Beef
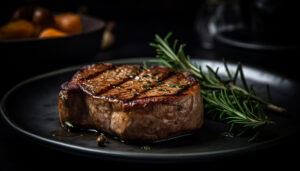
Boxed beef and trim moved lower as weekly production recovered, but seasonal rib strength persisted. Year-to-date output remains below last year, and new screwworm cases could delay a cattle-import reopening. Separate rib requirements from trim and other beef needs when evaluating portfolio-wide purchasing exposure.
Outlook: Improved supplies should moderate fall beef pricing, but rib seasonality and cattle-import disruption could limit relief in specific categories.
Pork
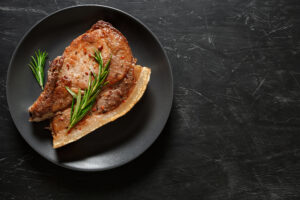
The pork cutout reached a more-than-three-year low, led lower by hams and ribs, while bellies remained sharply below year-earlier levels. Weekly production declined, but a substantial fourth-quarter seasonal increase is forecast. Buyers can reassess pork’s relative value across concepts without assuming every cut moves together.
Outlook: Higher projected fourth-quarter production and lackluster consumption favor continued pork-price pressure, despite constrained hog slaughter.
Produce
Iceberg lettuce’s rally, rising tomatoes and an unexpected potato increase are complicating produce budgets, while Hass avocados continue to soften. Western growing issues remain unresolved. Multiunit teams should distinguish commodity-wide pressure from location-specific invoice changes and consider approved menu alternatives where specifications allow.
Outlook: Lettuce and tomato pressure should persist near term, with eventual potato relief and avocado stabilization offering only partial offsets.
Dairy
Spot dairy strengthened broadly, with record whey pricing and cheese blocks at a one-year high; nonfat dry milk was the exception. Milk availability is improving seasonally, and cheese inventories are adequate to ample. Procurement teams should distinguish current exchange moves from the lagged signals affecting distributor cheddar pricing.
Outlook: Distributor cheddar is expected to soften over the coming weeks, but recent spot gains argue against assuming uninterrupted dairy-cost declines.
Grains
Corn outperformed a broadly weaker grain complex but approached the closely watched $4.80 level. Export sales improved, and the global balance sheet remains tight. For multiunit planning, use alternative grain-cost scenarios rather than treating a futures move as an automatic change in contracted or delivered costs.
Outlook: A break below $4.80 could expose corn to $4.40, while export demand may help stabilize the market.
Seafood
Fresh yellowfin tuna’s sharp August increase interrupted a prolonged period of below-normal pricing. Easing import volumes and the commentary’s longer-term recovery view warrant attention when setting seafood assumptions. Keep near-term purchasing plans separate from longer-horizon exposure rather than extrapolating one month’s increase across the portfolio.
Outlook: Yellowfin may soften modestly through year-end before a January increase, with further upside risk into 2027 and beyond.
Need Help Managing Market Volatility?
Consolidated Concepts offers custom contract support, commodity tracking, and supply chain solutions to help operators thrive-no matter the market conditions. Reach out to see how we can help your business stay ahead of pricing swings and supply uncertainty.